


From new equipment and tire inventory to garage construction and business expansion, Auto Shop Lend helps automotive businesses find financing options to keep their shops running and growing.

Paint booth financing and automotive analyzer financing can help qualified auto repair businesses purchase specialized equipment for collision work, diagnostics, and modern vehicle servicing. Auto service business purchase financing, drivetrain repair financing, and tire shop financing may provide funding for business acquisitions, specialized repair equipment, inventory, expansion, and other eligible automotive business expenses.
Financing options designed around the needs of automotive repair and service businesses.
Get the funding you need to keep the parts, tires, and products your customers need in stock.
Upgrade the tools and equipment that help your technicians work efficiently and serve more customers.
Take your shop to the next level with financing options for improvements, expansion, and growth.
Whether you’re looking for equipment, inventory, construction, repairs, or expansion financing, start by telling us about your business and what you’re looking to accomplish.
Your shop is different from a typical business. Your financing needs can involve equipment, inventory, facilities, vehicles, tools, and expansion.
Whether you need inventory financing, construction financing, or funding for your next expansion, explore options for the needs that matter to your business.
When equipment needs replacing or inventory needs replenishing, access to the right financing can help you keep your business operating.
Opening another location? Expanding your garage? Adding services? Financing can help you turn your next business opportunity into a plan.
Affiliate Disclosure: We are an affiliate marketing website and may receive compensation from lending partners. We are not a lender, do not make credit decisions, and do not guarantee approval. Loan terms and rates are determined by individual lenders.
From everyday business needs to major expansion projects, explore financing options designed around automotive businesses and the work they do every day.
Auto Shop Lend focuses on financing for automotive businesses. The site helps shop owners explore financing options for business needs such as equipment, inventory, construction, expansion, and other shop-related expenses.
Depending on the financing option, funds may be used for business needs such as equipment, inventory, facility improvements, construction, expansion, and other qualified expenses.
Auto shops often need specialized equipment to operate and grow. Auto Shop Lend helps businesses explore financing options for equipment and other business needs.
Tire inventory can represent a significant expense for tire dealers and automotive service businesses. Inventory financing can help eligible businesses explore funding for stocking the products they need.
Garage construction financing can help eligible automotive businesses explore funding for building, expanding, or improving their facilities.
Yes. Auto repair shop expansion may require additional space, equipment, inventory, or facility improvements. Auto Shop Lend helps businesses explore financing options for these types of growth projects.
Transmission shops have specialized equipment, tools, inventory, and operating needs. Auto Shop Lend provides financing-focused resources for automotive businesses looking for funding options.
Modern automotive businesses require significant capital to remain competitive. A repair facility may need diagnostic systems, vehicle lifts, compressors, tire machines, transmission equipment, collision-repair technology, inventory, and sufficient working capital to handle everyday expenses. Owners who want to grow may face even larger investments when purchasing another business or expanding into new services.
Understanding options such as Paint booth financing, auto service business purchase financing, automotive analyzer financing, drivetrain repair financing, and tire shop financing can help owners identify funding strategies for different business objectives. Financing is not automatically appropriate for every investment, however. Owners should evaluate the cost, expected financial benefit, repayment requirements, and effect on cash flow before accepting an obligation.
This guide examines several major automotive financing needs and explains how business owners can prepare for equipment purchases, acquisitions, and expansion.
Automotive technology continues to evolve, and repair businesses must often invest to keep their equipment and capabilities current. A shop that once handled most repairs with mechanical tools may now need sophisticated electronic diagnostic systems, computerized alignment equipment, calibration technology, and specialized machinery.
For collision businesses, Paint booth financing may help qualified owners spread the cost of purchasing or upgrading refinishing equipment. A modern paint-booth project can involve more than the booth itself, including ventilation, electrical work, fire-suppression systems, installation, permits, and facility modifications.
Entrepreneurs purchasing an established operation have a different need. Auto service business purchase financing may potentially provide capital toward an eligible acquisition, depending on the financing provider and qualifications of the buyer and business.
Regardless of the purpose, owners should begin by determining exactly how much capital is required and what the investment is expected to accomplish.
Collision repair can be particularly capital intensive. Paint booths, frame machines, measuring systems, welders, compressors, lifts, and refinishing equipment can represent major investments.
Paint booth financing may help preserve working capital by allowing qualified businesses to finance an eligible equipment purchase rather than paying the entire cost immediately.
Before financing a booth, management should calculate the complete installed cost. An equipment quote may not include every expense required to make the system operational.
The business should investigate building modifications, electrical requirements, ventilation, installation, training, maintenance, and other associated expenses. Applicable building, fire, environmental, and occupational requirements should also be investigated before construction or installation begins.
Owners should obtain professional guidance appropriate to their location and project rather than assuming one set of requirements applies everywhere.
Purchasing an established repair business can offer advantages over starting from scratch. The buyer may acquire equipment, employees, customers, supplier relationships, operating systems, and an established local reputation.
Auto service business purchase financing can potentially help qualified entrepreneurs fund an eligible ownership transition.
However, an established company should not be considered a good investment merely because it has been operating for many years.
Buyers should examine financial statements, tax returns, payroll, equipment, leases, debts, customer concentration, vendor relationships, employee retention, online reputation, and other important factors.
A buyer should also understand why the current owner is selling.
Retirement may present a very different situation from an owner leaving because revenue has been declining.
Vehicle diagnostics have become increasingly technology dependent. Modern repair facilities may rely on scan tools, oscilloscopes, electrical testing systems, emissions equipment, computerized analyzers, and other specialized technology.
Automotive analyzer financing may help qualified shops acquire eligible diagnostic equipment without paying the entire cost upfront.
The financial analysis should begin with utilization.
How often will technicians use the equipment? Will it allow the shop to perform work currently referred elsewhere? Can it reduce diagnostic time? Will employees require additional training or software subscriptions?
These questions help determine whether a new analyzer is likely to produce enough business value to justify its cost.
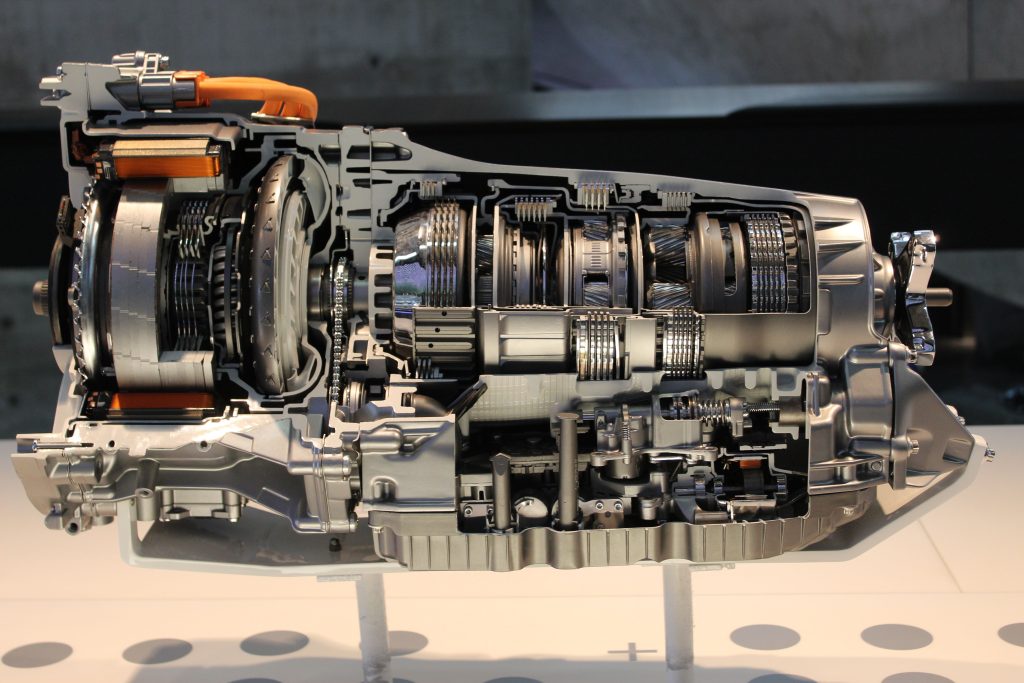
Transmission, differential, axle, clutch, transfer-case, and related services can require specialized tools and experienced technicians.
Drivetrain repair financing may potentially support eligible equipment or other investments required to develop or expand these capabilities.
Before expanding, management should evaluate local customer demand.
Specialized repair services can produce valuable revenue opportunities, but expensive equipment is useful only when enough customers need the service.
Owners should calculate anticipated repair volume, average gross profit, labor requirements, equipment expenses, training costs, and additional overhead before making a substantial investment.
Tire dealers have significant equipment and inventory requirements.
Tire shop financing may potentially help qualified businesses purchase eligible equipment, inventory, facility improvements, or other business assets.
A tire operation may require tire changers, wheel balancers, alignment systems, lifts, compressors, diagnostic equipment, storage racks, and substantial inventory.
Inventory deserves particular attention because money invested in tires remains tied up until those products are sold.
Management should monitor inventory turnover and identify which products move quickly before using borrowed money to increase stock.
The following graph shows an illustrative $500,000 automotive business investment. These figures are examples only and are not industry averages, lender requirements, quotations, or promises of financing.
Business acquisition          $200,000 | ████████████████████
Shop equipment                $100,000 | ██████████
Diagnostic technology          $70,000 | ███████
Facility improvements          $60,000 | ██████
Inventory                      $40,000 | ████
Working capital $30,000 | ███| Example Use of Funds | Illustrative Amount |
|---|---|
| Business acquisition | $200,000 |
| Shop equipment | $100,000 |
| Diagnostic technology | $70,000 |
| Facility improvements | $60,000 |
| Inventory | $40,000 |
| Working capital | $30,000 |
| Total | $500,000 |
A use-of-funds budget can help owners avoid borrowing based on a rough estimate. It can also expose expenses that might otherwise be overlooked.
Before applying for Paint booth financing, owners should develop a project budget rather than simply using the equipment’s advertised price.
Suppose the booth itself costs $80,000. The project could also require electrical upgrades, concrete or structural work, ventilation improvements, installation, permits, training, and modifications to surrounding workspace.
Those additional expenses can materially change the project’s financial requirements.
Owners should also estimate how the investment will affect production. If an improved system increases throughput or reduces outsourcing, management can estimate the potential economic benefit and compare it with the financing obligation.
The goal is to connect borrowing with measurable business results.
When evaluating auto service business purchase financing, buyers should focus on sustainable cash flow rather than sales alone.
A company generating $2 million in annual revenue is not necessarily more valuable than a company generating $1 million.
What matters is what remains after parts, payroll, occupancy costs, insurance, advertising, taxes, maintenance, and other expenses.
Buyers should determine whether the business can reasonably support acquisition debt while maintaining sufficient working capital.
The purchase price should also be evaluated independently rather than accepted simply because the seller believes the business is worth a particular amount.
When considering automotive analyzer financing, owners can evaluate the equipment as a productive business asset.
Suppose technicians currently spend significant time diagnosing complex electrical problems. A more advanced analyzer might reduce diagnostic time or help the business accept repairs it currently declines.
Management can estimate the additional billable hours or retained jobs associated with that capability.
Equipment financing still introduces repayment obligations, so projected benefits should be based on conservative assumptions.
A best-case forecast is rarely an adequate basis for taking on long-term debt.
A business considering drivetrain repair financing should determine whether specialized services fit its existing customer base.
A general repair facility already servicing a large number of vehicles may have opportunities to retain drivetrain work that it currently refers to specialized businesses.
That does not necessarily mean purchasing every available machine is appropriate.
Management should identify which services are being outsourced most frequently and estimate whether bringing those jobs in-house could generate sufficient incremental gross profit.
Employee expertise is equally important. Equipment without trained technicians does not automatically create a profitable service department.
When evaluating tire shop financing, owners should distinguish between financing durable equipment and financing inventory.
A wheel balancer may remain productive for years, while tires are purchased specifically to be resold.
These different uses of capital have different financial characteristics.
Owners should examine historical sales and avoid accumulating excessive quantities of slow-moving inventory simply because financing is available.
An effective inventory strategy attempts to balance customer availability with efficient use of working capital.
Automotive owners researching financing should also understand the SBA 7(a) program. The U.S. Small Business Administration says 7(a) financing can be used for purposes including acquiring or improving real estate and buildings, short- and long-term working capital, purchasing and installing machinery and equipment, and complete or partial changes of ownership. The maximum 7(a) loan amount is currently $5 million.
That means an eligible business investigating Paint booth financing may want to compare conventional equipment products with SBA-backed financing where appropriate.
SBA financing is not an automatic approval. SBA states that eligible businesses must meet applicable requirements, including being creditworthy and demonstrating a reasonable ability to repay.
Because the 7(a) program permits complete or partial changes of ownership, it can also be worth researching when considering auto service business purchase financing.
An acquisition loan nevertheless needs to be supported by a viable transaction.
Buyers should carefully examine the target company’s historical performance and determine whether expected post-acquisition cash flow can support debt payments.
They should also calculate how much personal capital or other funding may be required and how much liquidity will remain after closing.
Purchasing a profitable business but exhausting every available dollar at closing can create cash-flow difficulties immediately after ownership changes.
Equipment purchases may also have tax consequences.
The IRS explains that depreciation generally allows taxpayers to recover the cost or other basis of qualifying business or income-producing property over time. Its guidance notes that many types of tangible business property, including machinery and equipment, can be depreciable when applicable requirements are satisfied.
That can be relevant when researching automotive analyzer financing, although financing and tax treatment are separate issues.
IRS Publication 946 — How to Depreciate Property
Owners should consult a qualified tax professional regarding their individual circumstances rather than assuming that a particular purchase qualifies for a specific deduction.
The same equipment-planning principles apply to drivetrain repair financing.
A transmission or driveline department may require specialized jacks, presses, lifts, diagnostic tools, cleaning equipment, rebuilding tools, and other machinery.
Before borrowing, management should identify which investments are essential and which could reasonably wait.
This prevents an owner from financing an entire wish list when only several pieces of equipment are necessary to begin generating additional revenue.
A phased investment strategy can sometimes reduce initial capital requirements while allowing the business to measure customer demand before expanding further.
Businesses investigating tire shop financing should create separate budgets for equipment and inventory.
This distinction can make cash-flow planning clearer.
Durable equipment may generate value over many years, while inventory should ideally convert back into cash through sales much more quickly.
Owners can monitor sales by tire size, brand, vehicle type, margin, and season to determine which products justify greater inventory investment.
Data-driven purchasing can help prevent valuable working capital from becoming concentrated in products customers rarely request.
An owner considering Paint booth financing should think about how long the equipment is expected to remain productive and compare that period with the proposed repayment structure.
The same principle applies to diagnostic equipment and other durable assets.
A financing term that substantially outlasts an asset’s useful economic life can create problems because the business may still owe money when replacement is necessary.
Conversely, an unnecessarily short repayment period can produce payments that put excessive pressure on cash flow.
Owners should compare multiple structures when possible.
With auto service business purchase financing, financial due diligence is essential.
Buyers should investigate revenue trends, gross margins, operating expenses, payroll, debt, equipment condition, lease obligations, customer concentration, and working-capital requirements.
They should also understand exactly which assets are included.
An acquisition could involve tools, equipment, inventory, trade names, websites, phone numbers, customer records, intellectual property, and other assets.
Legal and accounting professionals can help buyers understand transaction documents and financial information before a binding commitment is made.
When using automotive analyzer financing, owners should estimate the potential financial return before buying.
Consider how many additional diagnostic jobs the equipment could support each month and the expected gross profit from those services.
Then subtract software, maintenance, training, financing, and other incremental costs.
The resulting estimate will not guarantee future performance, but it gives management a more rational framework for evaluating the purchase.
Equipment should ideally solve a demonstrated business need rather than simply add another technology to the shop floor.
For shops using drivetrain repair financing, staffing should be considered alongside equipment.
Transmission and driveline repairs can require specialized technical knowledge.
A business that purchases expensive equipment without qualified employees may struggle to produce sufficient revenue from its investment.
Management should therefore create an integrated plan covering equipment, hiring, training, marketing, parts sourcing, warranty procedures, and workflow.
The objective should be building a profitable service capability rather than simply purchasing machinery.
A growing dealer considering tire shop financing should identify the factor currently limiting expansion.
If customer demand exceeds existing capacity, the business might benefit from another service bay, additional equipment, more inventory, or another technician.
If demand is weak, however, expanding the facility may not solve the problem.
Owners should examine appointment volume, technician utilization, equipment utilization, inventory turnover, gross margins, and customer acquisition before committing to a large expansion.
Capital works best when directed toward an identifiable constraint.
One potential advantage of Paint booth financing is that an owner may preserve cash instead of paying the entire project cost upfront.
Cash reserves can be important in automotive businesses because payroll, insurance, rent, utilities, parts, advertising, and other expenses continue regardless of weekly sales fluctuations.
Borrowing is not free, however.
Management should compare the cost of financing with the value of maintaining additional liquidity.
The correct decision depends on the company’s financial condition, available terms, and anticipated cash requirements.
Buyers using auto service business purchase financing should prepare for what happens immediately after closing.
Employees may have questions about their jobs. Vendors may need updated account information. Customers may want reassurance that service standards will remain consistent.
The buyer should determine whether the seller will assist during a transition period and identify relationships that depend heavily on the departing owner.
Protecting existing customer and employee relationships can be critical to preserving the value purchased.
A business using automotive analyzer financing should budget for employee training where needed.
Technology creates value only when technicians can use it effectively.
Training expenses and temporary reductions in productivity should therefore be considered part of the investment rather than unexpected costs.
Owners should also investigate software subscriptions and update requirements.
Some automotive technology carries recurring expenses that continue long after the original equipment purchase.
Before accepting drivetrain repair financing, owners can review existing repair orders to determine how frequently customers request work the shop currently cannot perform.
This provides actual internal data rather than relying entirely on market assumptions.
If the business refers a meaningful volume of profitable drivetrain jobs elsewhere, developing internal capabilities may deserve further investigation.
If only a handful of customers request these services each year, a major equipment investment may be harder to justify.
Owners researching tire shop financing should consider expansion in stages.
A business might initially add a tire changer and balancer, then expand inventory once sales patterns become clearer. Later, it could add alignment capabilities or additional service bays if customer demand supports them.
A staged approach can allow management to evaluate performance after each investment.
It also reduces the risk of committing substantial capital to several untested assumptions simultaneously.
Automotive businesses rarely operate with only one financial need.
A collision center considering Paint booth financing may simultaneously require facility improvements and additional working capital. An entrepreneur researching auto service business purchase financing may need money for the acquisition plus capital for repairs, inventory, payroll, and equipment replacements after closing.
A general repair facility considering automotive analyzer financing may need to coordinate its equipment purchase with technician training. A company exploring drivetrain repair financing may need specialized equipment and experienced employees.
Likewise, a growing dealer evaluating tire shop financing should account for equipment, inventory, employees, marketing, and facility capacity.
Creating one comprehensive capital plan can provide a clearer picture than financing each expense independently without considering the company’s total debt burden.
For additional information about financing an automotive company, owners can visit AutoShopLend as an internal starting point. Relevant pages on your site covering equipment financing, shop acquisitions, working capital, tire businesses, or repair-shop expansion can also be linked contextually throughout this article once their exact URLs are confirmed.
Using accurate internal URLs is important. I have not invented page addresses that I could not verify.
Automotive financing should ultimately support productive investments rather than borrowing for its own sake.
Owners considering Paint booth financing should calculate the complete installed project cost and determine whether the investment addresses a genuine production need. Buyers researching auto service business purchase financing should conduct thorough financial and operational due diligence before agreeing to a purchase price.
Shops considering automotive analyzer financing should evaluate equipment utilization, training, software expenses, and expected productivity improvements. Businesses exploring drivetrain repair financing should confirm that customer demand and technician expertise justify specialized investments. Dealers evaluating tire shop financing should pay particular attention to equipment utilization, inventory turnover, and working-capital requirements.
The SBA’s financing programs and IRS guidance can provide useful starting points for research, but individual lending and tax situations vary. Owners should compare actual financing agreements carefully and obtain qualified financial, legal, or tax advice when appropriate.