


From new equipment and tire inventory to garage construction and business expansion, Auto Shop Lend helps automotive businesses find financing options to keep their shops running and growing.

Automotive business expansion loans and heavy duty repair shop funding can help qualified automotive businesses invest in larger facilities, specialized equipment, additional service bays, and other eligible growth expenses. Owners researching auto shop real estate financing can compare available auto shop loans and apply for auto shop loans that fit their property, equipment, working capital, or expansion needs.
Financing options designed around the needs of automotive repair and service businesses.
Get the funding you need to keep the parts, tires, and products your customers need in stock.
Upgrade the tools and equipment that help your technicians work efficiently and serve more customers.
Take your shop to the next level with financing options for improvements, expansion, and growth.
Whether you’re looking for equipment, inventory, construction, repairs, or expansion financing, start by telling us about your business and what you’re looking to accomplish.
Your shop is different from a typical business. Your financing needs can involve equipment, inventory, facilities, vehicles, tools, and expansion.
Whether you need inventory financing, construction financing, or funding for your next expansion, explore options for the needs that matter to your business.
When equipment needs replacing or inventory needs replenishing, access to the right financing can help you keep your business operating.
Opening another location? Expanding your garage? Adding services? Financing can help you turn your next business opportunity into a plan.
Whether you’re building a new garage, adding equipment, stocking up on inventory, or expanding your automotive business, Auto Shop Lend can help you explore financing options for your next move.
Affiliate Disclosure: We are an affiliate marketing website and may receive compensation from lending partners. We are not a lender, do not make credit decisions, and do not guarantee approval. Loan terms and rates are determined by individual lenders.
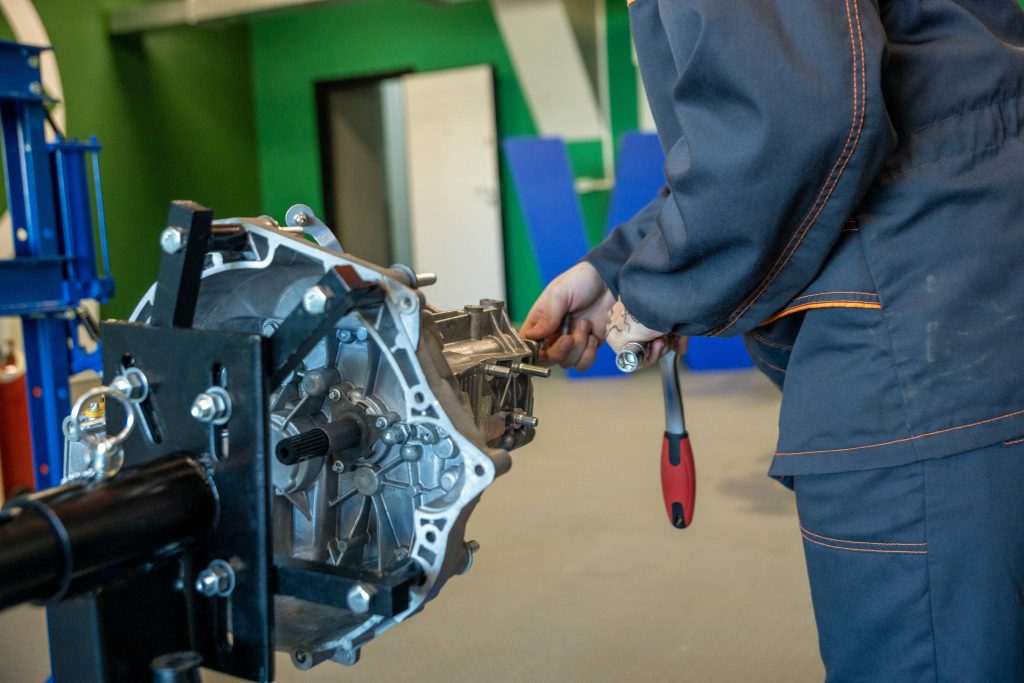
From everyday business needs to major expansion projects, explore financing options designed around automotive businesses and the work they do every day.
Auto Shop Lend focuses on financing for automotive businesses. The site helps shop owners explore financing options for business needs such as equipment, inventory, construction, expansion, and other shop-related expenses.
Depending on the financing option, funds may be used for business needs such as equipment, inventory, facility improvements, construction, expansion, and other qualified expenses.
Auto shops often need specialized equipment to operate and grow. Auto Shop Lend helps businesses explore financing options for equipment and other business needs.
Tire inventory can represent a significant expense for tire dealers and automotive service businesses. Inventory financing can help eligible businesses explore funding for stocking the products they need.
Garage construction financing can help eligible automotive businesses explore funding for building, expanding, or improving their facilities.
Yes. Auto repair shop expansion may require additional space, equipment, inventory, or facility improvements. Auto Shop Lend helps businesses explore financing options for these types of growth projects.
Transmission shops have specialized equipment, tools, inventory, and operating needs. Auto Shop Lend provides financing-focused resources for automotive businesses looking for funding options.
Growing an automotive repair business requires more than technical knowledge and a steady flow of customers. Owners may eventually need larger facilities, additional service bays, specialized equipment, commercial property, new technicians, inventory, diagnostic technology, and working capital. Each investment can create opportunities, but each also needs to be evaluated against expected revenue and the company’s ability to handle additional financial obligations.
Financing can provide a way to spread major business investments over time instead of paying the entire cost from cash reserves. However, borrowing should be tied to a specific business purpose and realistic financial projections. The following sections examine how automotive companies can approach expansion, heavy-duty operations, property acquisition, equipment purchases, and financing decisions.
Growth should begin with a written plan identifying exactly where additional capacity is needed. Automotive business expansion loans may be considered when qualified companies need capital for eligible equipment, renovations, additional service capacity, or other growth-related expenditures.
Businesses servicing trucks and commercial vehicles have additional requirements. heavy duty repair shop funding could potentially support eligible investments in larger service equipment, specialized tools, diagnostic technology, or facility improvements.
Property can represent an even larger investment. auto shop real estate financing may be worth investigating when an owner wants to purchase, construct, or improve a location rather than continue leasing.
Before owners apply for auto shop loans, they should determine how much money is actually required and how the resulting payments will affect monthly cash flow.
A useful expansion plan should estimate construction and equipment costs, anticipated additional revenue, technician requirements, operating expenses, and a contingency reserve. Businesses should also consider how long it may take before new investments reach full utilization.
Financing does not create demand by itself. Additional bays and equipment are most valuable when an established customer base or realistic growth strategy can keep them productive.
A successful repair operation can eventually outgrow its building. Limited parking, crowded bays, insufficient storage, and equipment bottlenecks can reduce productivity even when customer demand remains strong.
At that stage, Automotive business expansion loans can potentially help qualified owners address eligible improvements. The project might involve renovating an existing building, installing equipment, increasing shop capacity, or making other approved business investments.
A commercial vehicle operation may have more substantial requirements. heavy duty repair shop funding could be evaluated for eligible projects involving equipment and facilities designed around larger vehicles.
Owners who have been leasing may also compare expansion with property ownership. auto shop real estate financing can potentially provide a path toward acquiring an appropriate commercial location, subject to lender requirements and the economics of the transaction.
Businesses preparing to apply for auto shop loans should develop a detailed use-of-funds statement rather than requesting an arbitrary amount.
Management should know whether insufficient space is truly limiting revenue. If existing bays frequently sit unused, constructing additional ones may simply increase overhead. If technicians are consistently booked and customers are being turned away, expansion may deserve stronger consideration.
Heavy-duty vehicle service can require substantial investments. Commercial trucks, fleet vehicles, buses, and other large vehicles may need appropriately sized bays, lifts, diagnostic systems, tools, storage, and parking.
For those businesses, heavy duty repair shop funding may help qualified companies finance eligible investments needed to establish or expand commercial repair capabilities.
An existing light-duty operation adding commercial services might simultaneously consider Automotive business expansion loans when the project requires broader facility improvements or additional capacity.
Real estate is especially important for operations handling large vehicles. auto shop real estate financing may be considered when purchasing a property with adequate access, parking, building dimensions, and room for equipment.
Before businesses apply for auto shop loans, owners should estimate expected commercial repair volume and determine whether the additional revenue can reasonably support financing payments and higher operating expenses.
Fleet work can provide recurring business, but customer concentration deserves attention. Depending heavily on one commercial account can expose a shop to financial risk if the customer changes providers or reduces its fleet.
Management should evaluate prospective fleet agreements, payment terms, labor requirements, parts expenses, technician availability, equipment utilization, and margins before making a substantial investment.
Property ownership can give an established automotive company greater control over its location, but purchasing commercial real estate introduces expenses that do not exist with many equipment purchases.
Businesses considering auto shop real estate financing should examine the complete transaction, including acquisition price, required improvements, inspections, professional services, and other applicable expenses.
If a larger property forms part of an overall growth strategy, Automotive business expansion loans might also be evaluated for qualifying investments that extend beyond the real estate itself.
A truck-focused facility may need significant modifications, making heavy duty repair shop funding another option to research for eligible equipment or facility-related expenses.
Owners preparing to apply for auto shop loans should evaluate a property’s suitability before concentrating exclusively on the financing payment.
Parking, zoning, accessibility, ceiling height, service-bay dimensions, electrical capacity, drainage, storage, environmental considerations, signage, and future expansion possibilities can all influence whether a property is appropriate for automotive use.
Buying an inexpensive building that requires extensive modifications can ultimately be more expensive than acquiring a property already suited to the company’s operations. Appropriate legal, environmental, real-estate, accounting, and construction professionals can be valuable during major transactions.
Consider a hypothetical automotive company planning an $800,000 expansion. These figures are illustrative only. They are not industry averages, financing offers, lender requirements, or estimates of what a particular project should cost.
| Example Use of Capital | Illustrative Amount |
|---|---|
| Commercial property | $350,000 |
| Building improvements | $150,000 |
| Service equipment | $120,000 |
| Diagnostic technology | $60,000 |
| Parts and inventory | $65,000 |
| Working capital | $55,000 |
| Total | $800,000 |
Commercial property       $350,000 | ███████████████████████████████████
Building improvements      $150,000 | ███████████████
Service equipment          $120,000 | ████████████
Parts and inventory         $65,000 | ███████
Diagnostic technology       $60,000 | ██████
Working capital             $55,000 | ██████
A company undertaking this hypothetical project could investigate auto shop real estate financing for an eligible property transaction while evaluating Automotive business expansion loans for qualifying improvements or equipment.
If commercial vehicle service is part of the plan, heavy duty repair shop funding may also deserve consideration for eligible specialized investments.
Before owners apply for auto shop loans, breaking the project into individual categories helps establish how much capital is actually required.
This approach can also prevent overborrowing. A business might discover that some equipment can be purchased later, that existing inventory is sufficient, or that certain renovations are optional. Separating essential investments from desirable improvements can produce a more disciplined capital plan.
The U.S. Small Business Administration’s 7(a) loan program is one financing resource automotive businesses may want to investigate. The SBA identifies permitted uses that include acquiring, refinancing, or improving real estate and buildings; working capital; purchasing and installing machinery and equipment; supplies; and complete or partial ownership changes.
Those permitted uses mean businesses evaluating Automotive business expansion loans may want to compare conventional commercial products with SBA-backed financing when the project and borrower qualify.
An operation investigating heavy duty repair shop funding can similarly research whether eligible machinery, equipment, real estate, or working-capital expenses fit an SBA-backed transaction.
For owners interested in purchasing property, auto shop real estate financing can also be compared with applicable SBA options.
Businesses preparing to apply for auto shop loans should understand that SBA backing does not guarantee approval. Participating lenders still evaluate applicants, and SBA eligibility requirements apply.
The maximum individual SBA 7(a) loan amount is currently $5 million. For authoritative program information, visit the SBA 7(a) Loan Program. Business owners can also review the SBA information for borrowers and lenders.
Borrowers should compare available financing based on the complete terms of an actual offer rather than assuming that one program is automatically best for every automotive business.
Facility expansion frequently creates a need for additional equipment. Vehicle lifts, compressors, diagnostic systems, alignment equipment, tire machines, transmission tools, shop-management technology, and other assets can represent a substantial portion of a growth budget.
Automotive business expansion loans can potentially help qualified companies address eligible equipment and facility needs as part of a larger project.
Commercial operations may require more specialized machinery. heavy duty repair shop funding could potentially help finance eligible equipment designed for servicing trucks or fleet vehicles.
Equipment strategy should also influence property decisions. When a company uses auto shop real estate financing to acquire a building, management should confirm that the property can physically and operationally support planned machinery before completing the transaction.
Before businesses apply for auto shop loans, owners should calculate the complete cost of equipment rather than relying only on purchase prices. Installation, electrical upgrades, software, calibration, maintenance, training, and eventual replacement can add to the investment.
Equipment purchases can have tax consequences as well. The IRS explains depreciation rules for qualifying business property in Publication 946. The publication discusses machinery, equipment, buildings, vehicles, and other depreciable property.
For federal tax information, see IRS Publication 946 — How to Depreciate Property. Businesses should consult an appropriate tax professional about their individual circumstances rather than assuming a specific purchase will receive particular tax treatment.
Expansion can strain cash even when the long-term project is financially sound. Construction delays, equipment installation, hiring, marketing, inventory purchases, and unexpected repairs can occur before the investment produces its expected revenue.
Owners using Automotive business expansion loans should therefore consider how financing payments interact with existing payroll, rent, insurance, taxes, utilities, supplier obligations, and debt.
Businesses relying on heavy duty repair shop funding should be particularly careful when expensive specialized equipment will require time to reach full utilization.
Property transactions create additional fixed expenses. Companies evaluating auto shop real estate financing should estimate occupancy costs using conservative revenue assumptions rather than expecting immediate growth.
Before owners apply for auto shop loans, they should review cash-flow projections under more than one scenario. A plan can examine expected performance alongside a slower-growth scenario to determine whether the company has enough financial flexibility.
Working capital should not be an afterthought. Spending every available dollar on property and machinery can leave an otherwise successful company unable to comfortably handle ordinary expenses or unexpected problems.
Owners should understand financing rates, fees, repayment frequency, collateral requirements, guarantees, prepayment terms, and other contractual provisions before accepting an offer.
Financing should ultimately help an automotive company solve a measurable business problem or pursue a well-supported opportunity.
Before pursuing Automotive business expansion loans, management should determine whether customer demand, technician productivity, or capacity limitations justify the investment. Growth for its own sake can increase revenue without necessarily increasing profitability.
A business evaluating heavy duty repair shop funding should understand its target commercial customers, expected service volume, technician requirements, equipment needs, and competitive environment.
Owners considering auto shop real estate financing should evaluate whether purchasing property supports the company’s long-term strategy and whether projected cash flow can reasonably handle the associated obligations.
When businesses apply for auto shop loans, financing should be compared on more than the amount offered. Repayment structure, total borrowing cost, fees, collateral, flexibility, and alignment with the financed asset can all matter.
Successful expansion generally depends on more than access to money. Customer demand, skilled employees, efficient operations, accurate pricing, cost controls, cash reserves, and responsible financial management all contribute to the outcome.
Automotive businesses have many reasons to seek capital. An established repair operation may need additional bays, a truck specialist may require larger equipment, or a growing company may decide that purchasing commercial property makes more sense than continuing to lease.
Whatever the objective, the financing process should begin with a detailed budget. Owners should know exactly where borrowed money will go, what additional costs the investment creates, and what level of revenue or productivity is needed to support repayment.
Property, equipment, working capital, and construction should also be evaluated according to their different financial characteristics. A long-lived commercial building is fundamentally different from short-term operating expenses, while specialized machinery has its own expected productive life and maintenance requirements.
SBA and IRS resources provide useful authoritative starting points for researching financing programs and federal depreciation rules. Actual eligibility, rates, fees, repayment terms, tax treatment, and approval decisions depend on the individual business, transaction, lender, and applicable requirements.