


From new equipment and tire inventory to garage construction and business expansion, Auto Shop Lend helps automotive businesses find financing options to keep their shops running and growing.

EV battery service equipment financing and automotive digital workflow financing may help qualified automotive businesses invest in specialized EV equipment and technology designed to improve shop operations. Owners comparing mechanic business financing options and fleet maintenance financing can explore potential funding solutions for eligible equipment, technology, working capital, and business expansion needs.
Financing options designed around the needs of automotive repair and service businesses.
Get the funding you need to keep the parts, tires, and products your customers need in stock.
Upgrade the tools and equipment that help your technicians work efficiently and serve more customers.
Take your shop to the next level with financing options for improvements, expansion, and growth.
Whether you’re looking for equipment, inventory, construction, repairs, or expansion financing, start by telling us about your business and what you’re looking to accomplish.
Your shop is different from a typical business. Your financing needs can involve equipment, inventory, facilities, vehicles, tools, and expansion.
Whether you need inventory financing, construction financing, or funding for your next expansion, explore options for the needs that matter to your business.
When equipment needs replacing or inventory needs replenishing, access to the right financing can help you keep your business operating.
Opening another location? Expanding your garage? Adding services? Financing can help you turn your next business opportunity into a plan.
Whether you’re building a new garage, adding equipment, stocking up on inventory, or expanding your automotive business, Auto Shop Lend can help you explore financing options for your next move.
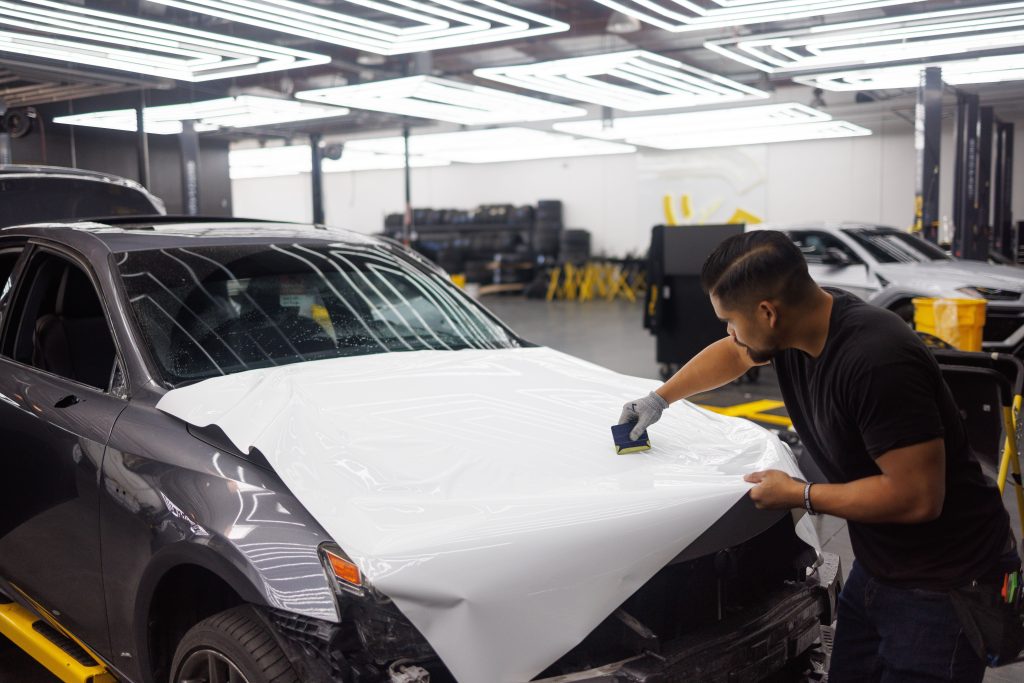
From everyday business needs to major expansion projects, explore financing options designed around automotive businesses and the work they do every day.
Auto Shop Lend focuses on financing for automotive businesses. The site helps shop owners explore financing options for business needs such as equipment, inventory, construction, expansion, and other shop-related expenses.
Depending on the financing option, funds may be used for business needs such as equipment, inventory, facility improvements, construction, expansion, and other qualified expenses.
Auto shops often need specialized equipment to operate and grow. Auto Shop Lend helps businesses explore financing options for equipment and other business needs.
Tire inventory can represent a significant expense for tire dealers and automotive service businesses. Inventory financing can help eligible businesses explore funding for stocking the products they need.
Garage construction financing can help eligible automotive businesses explore funding for building, expanding, or improving their facilities.
Yes. Auto repair shop expansion may require additional space, equipment, inventory, or facility improvements. Auto Shop Lend helps businesses explore financing options for these types of growth projects.
Transmission shops have specialized equipment, tools, inventory, and operating needs. Auto Shop Lend provides financing-focused resources for automotive businesses looking for funding options.
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Ut elit tellus, luctus nec ullamcorper mattis, pulvinar dapibus leo.
The automotive repair industry is becoming more technologically demanding. Traditional mechanical service remains essential, but modern shops increasingly need advanced diagnostic systems, digital management platforms, specialized electric-vehicle tools, technician training, and equipment capable of supporting commercial fleets.
These investments can create substantial capital requirements. A repair business might need to upgrade technology while preserving enough cash for payroll, parts, utilities, insurance, marketing, and other operating expenses. A shop entering the electric-vehicle market may also need facility improvements and specialized safety equipment before it can provide certain services effectively.
Financing can potentially help qualified businesses distribute eligible investment costs over time. The appropriate structure, however, depends on what is being purchased, the financial condition of the business, and the expected economic benefit of the investment.
The following sections examine important considerations for automotive businesses planning technology, EV, equipment, and fleet-service investments.
Electric vehicles are creating new opportunities for independent repair businesses, dealerships, specialty shops, and other automotive service operations. EV battery service equipment financing may help qualified businesses acquire eligible equipment required for certain battery-related diagnostic, maintenance, and service operations.
Technology is changing the administrative side of the shop as well. automotive digital workflow financing may potentially support qualifying investments in software or technology used to organize repair orders, inspections, customer communication, scheduling, and other operational processes.
Owners should compare several mechanic business financing options before committing to a particular structure. Equipment financing, term loans, lines of credit, SBA-backed products, and other forms of business financing can serve different purposes.
Commercial accounts create another opportunity. fleet maintenance financing may help qualified automotive businesses make eligible investments needed to develop or expand services for companies operating multiple vehicles.
Before borrowing, management should identify exactly what the investment is intended to accomplish.
A new piece of equipment might allow technicians to perform work currently referred elsewhere. Digital technology might reduce administrative inefficiencies. Fleet investments could allow a shop to handle larger commercial accounts.
Connecting financing to measurable business objectives can help management determine whether the proposed investment is financially reasonable.
Servicing electrified vehicles can require equipment beyond what is typically found in a conventional repair facility. Depending on the services offered, shops may need battery diagnostic systems, insulated tools, lifting or handling equipment, safety equipment, and other specialized technology.
EV battery service equipment financing can potentially help qualified businesses acquire eligible equipment while preserving additional existing capital.
Equipment alone is not enough. Employees need appropriate knowledge, procedures, and training for the services they perform.
Technology can support those operations. automotive digital workflow financing may help qualified shops acquire eligible digital systems used to organize inspections, repair documentation, customer approvals, technician assignments, and related information.
Owners should compare mechanic business financing options according to total cost, repayment schedule, qualifications, collateral requirements, guarantees, and permitted uses.
Businesses serving commercial customers might also evaluate fleet maintenance financing when expanding their ability to service vehicles belonging to contractors, delivery companies, service businesses, or other fleet operators.
Demand should guide investment.
A business should analyze its customer base and local vehicle population before purchasing expensive specialized equipment. If EV-related repair demand remains limited in a particular market, management may choose a gradual investment strategy rather than building maximum capacity immediately.
The objective is to create useful service capabilities without unnecessarily burdening the business with equipment and financing payments that cannot yet be supported by customer demand.
A repair order can involve numerous steps: scheduling, vehicle intake, inspection, diagnosis, estimating, customer authorization, parts ordering, technician assignment, repair documentation, invoicing, and payment.
automotive digital workflow financing may potentially help qualified businesses invest in eligible technology designed to connect some of these processes.
A shop developing electric-vehicle capabilities might combine technology improvements with EV battery service equipment financing for qualifying specialized equipment.
When reviewing mechanic business financing options, management should distinguish between long-lived equipment and recurring technology expenses. A financing structure appropriate for expensive machinery may not necessarily be ideal for a software subscription.
Businesses expanding commercial services may also investigate fleet maintenance financing to support eligible equipment, technology, or other investments associated with fleet-service operations.
Digital systems should solve specific operational problems.
For example, digital inspections can help technicians document vehicle condition with photographs and notes. Integrated repair-order systems can potentially reduce duplicate data entry. Scheduling systems can improve visibility into upcoming workloads, while centralized reporting can give owners a clearer view of shop performance.
Before investing, owners should examine implementation costs, employee training requirements, software integrations, subscription expenses, data portability, and ongoing support.
Technology produces its greatest value when employees consistently use it. An expensive system that is poorly implemented can become another overhead expense rather than an operational improvement.
Commercial fleet customers can provide recurring service opportunities, but they can also create new operational demands. Businesses may need additional bays, technicians, diagnostic systems, heavier-duty equipment, parts inventory, and administrative capabilities.
fleet maintenance financing may potentially help qualified repair businesses fund eligible investments associated with expanding commercial service capacity.
As fleets incorporate electric vehicles, shops may also investigate EV battery service equipment financing for eligible specialized equipment.
Technology can become particularly important when commercial customers require detailed service records. automotive digital workflow financing may help qualifying businesses acquire eligible systems for managing work orders, vehicle histories, inspections, approvals, and other documentation.
Owners should compare mechanic business financing options before deciding how to fund expansion.
Fleet work should be analyzed carefully because high revenue does not automatically mean high profitability. Commercial accounts may negotiate pricing, expect rapid turnaround, or require specific payment terms.
Management can estimate labor requirements, parts costs, technician productivity, bay utilization, billing cycles, and expected gross profit before committing significant capital.
Cash-flow timing also deserves attention. If a commercial customer pays invoices on terms rather than immediately, the repair business may need enough working capital to cover payroll and parts while awaiting payment.
A sustainable fleet strategy balances customer volume with pricing, operational capacity, payment timing, and financing obligations.
Consider a hypothetical established repair business planning a $500,000 modernization and service-expansion project. These numbers are illustrative only and are not industry averages, lender quotes, financing offers, or recommended spending levels.
| Example Investment | Illustrative Amount |
|---|---|
| EV service and battery equipment | $130,000 |
| Diagnostic technology | $90,000 |
| Facility and electrical improvements | $85,000 |
| Fleet-service equipment | $75,000 |
| Digital systems and technology | $45,000 |
| Technician education and safety | $25,000 |
| Working-capital reserve | $50,000 |
| Total | $500,000 |
EV Service Equipment          $130,000  ██████████████████████████
Diagnostic Technology          $90,000  ██████████████████
Facility Improvements          $85,000  █████████████████
Fleet-Service Equipment        $75,000  ███████████████
Operating Reserve              $50,000  ██████████
Digital Systems                $45,000  █████████
Education & Safety             $25,000  █████
In this hypothetical example, EV battery service equipment financing could potentially be considered for qualifying specialized equipment, while automotive digital workflow financing might be evaluated for eligible technology investments.
The owner could compare different mechanic business financing options for equipment, facility improvements, and working-capital requirements.
If commercial service represents a major part of the expansion, fleet maintenance financing might be investigated for qualifying investments associated with that side of the operation.
This example demonstrates why a project budget should include more than equipment. Technology, facility work, employee preparation, and liquidity can all affect whether an expansion succeeds.
Actual project expenses can vary considerably depending on location, equipment specifications, facility condition, services offered, and vendor pricing.
SBA-backed financing can provide another avenue for eligible automotive businesses making larger investments.
The SBA’s 7(a) program is its primary business loan program. Current SBA guidance states that eligible uses include acquiring or improving real estate and buildings, short- and long-term working capital, machinery and equipment, furniture and supplies, certain debt refinancing, and ownership changes. The maximum individual 7(a) loan amount is $5 million.
Businesses researching EV battery service equipment financing can therefore compare applicable SBA-backed alternatives when purchasing qualifying machinery or equipment.
Similarly, companies considering fleet maintenance financing may investigate SBA financing for qualifying equipment, facility, inventory, or working-capital investments.
Owners exploring automotive digital workflow financing should confirm whether their particular technology expenses qualify under the financing structure being considered rather than assuming every software expense is eligible.
Comparing mechanic business financing options can include conventional financing and applicable SBA-backed products. The SBA states that 7(a) applicants generally must operate for profit in the United States, meet applicable size requirements, be creditworthy, and demonstrate a reasonable ability to repay.
Owners can review the SBA 7(a) program and SBA financing program comparison directly.
As of July 4, 2026, qualified borrowers can combine up to $5 million through 7(a) with up to $5 million through 504 for up to $10 million in combined SBA-backed financing.
Financing should be evaluated according to total economic cost and business impact rather than the amount offered alone.
When comparing mechanic business financing options, owners can examine financing charges, fees, repayment frequency, maturity, collateral requirements, personal guarantees, prepayment provisions, and total expected repayment.
A business considering EV battery service equipment financing should also evaluate the useful life and expected utilization of the equipment.
For technology investments, automotive digital workflow financing should be compared against subscription costs, implementation expenses, employee training, and the expected operational benefit of the software.
Companies considering fleet maintenance financing should determine whether projected commercial service revenue can realistically support the resulting payment obligations.
The SBA’s current program comparison illustrates why matching financing duration with the underlying investment matters. It lists 7(a) maturities generally at 10 years or less unless real estate or equipment with a useful life exceeding 10 years is involved; real estate can extend to 25 years.
Owners should stress-test projected payments.
One scenario can reflect expected revenue and expenses. Another can assume lower sales, higher payroll, delayed expansion, or unexpected equipment costs.
A financing arrangement that remains manageable under conservative assumptions generally gives the business more flexibility than one requiring ideal conditions every month.
Financing an asset and determining its tax treatment are separate issues. Business owners should evaluate whether an investment makes operational and financial sense before considering potential tax benefits.
Businesses using EV battery service equipment financing should maintain accurate purchase and equipment records for their accountants.
Companies implementing technology through automotive digital workflow financing should similarly document costs and consult a qualified professional regarding the appropriate treatment of software, hardware, implementation expenses, and other technology expenditures.
Owners comparing mechanic business financing options should not assume a particular financing structure automatically creates a specific tax deduction.
The same principle applies to fleet maintenance financing used to acquire equipment or make facility investments.
IRS Publication 946 explains how taxpayers recover the cost of qualifying business or income-producing property through depreciation. The current publication states that, for tax years beginning in 2026, the maximum Section 179 expense deduction is $2.56 million, with the limit reduced when applicable property placed in service exceeds $4.09 million. Additional requirements and limitations apply.
Owners can review IRS Publication 946 and consult a qualified tax professional regarding their specific circumstances.
A potential deduction should never become the primary reason to purchase unnecessary equipment. The investment should first contribute to productive capacity, operational efficiency, customer service, or another legitimate business objective.
A sustainable financing strategy connects capital expenditures to realistic operational goals.
Before obtaining EV battery service equipment financing, owners should determine what services the equipment enables, whether technicians can use it appropriately, and whether local customer demand supports the investment.
Businesses considering automotive digital workflow financing should identify measurable improvements they expect from technology, such as better documentation, streamlined repair orders, reduced administrative work, or improved reporting.
When comparing mechanic business financing options, management should calculate how each potential payment fits within projected cash flow rather than simply pursuing the largest available amount.
Companies investigating fleet maintenance financing should analyze commercial customer demand, billing cycles, equipment requirements, staffing, and expected margins before expanding.
For additional automotive-business financing information, owners can visit AutoShopLend.
The strongest plan is not necessarily the one involving the most capital. It is the plan that gives the business enough resources to complete a productive project while maintaining sufficient liquidity and a manageable repayment obligation.
Automotive service businesses are entering a period in which physical equipment and digital infrastructure are increasingly connected. Shops may need sophisticated diagnostic systems, specialized EV tools, improved electrical infrastructure, digital repair-order technology, and stronger reporting systems while continuing to invest in traditional equipment and skilled employees.
Fleet service adds another dimension. Commercial customers can create recurring work, but serving them effectively may require additional capacity, faster turnaround, detailed documentation, specialized equipment, and sufficient working capital to handle billing cycles.
Owners should therefore begin with a project budget rather than a financing application.
Identify each proposed investment, obtain current vendor quotes, determine installation and implementation costs, estimate employee training requirements, and maintain an appropriate reserve for unexpected expenses. For an established operation, historical financial statements can help management determine how much additional debt the business can realistically support.
Different investments may also deserve different financing structures. Long-lived machinery, short-term working capital, technology subscriptions, and real-estate improvements do not necessarily belong under identical repayment schedules.
For eligible small businesses, SBA-backed financing is one potential avenue worth comparing. Current SBA guidance allows 7(a) proceeds to support qualifying working capital, machinery and equipment, real estate, supplies, and other permitted business purposes, with an individual 7(a) maximum of $5 million.
Financing can provide valuable resources, but it does not make an unproductive investment profitable. The underlying equipment, technology, or expansion should have a clear purpose and a realistic path toward supporting the resulting financial obligation.