


From new equipment and tire inventory to garage construction and business expansion, Auto Shop Lend helps automotive businesses find financing options to keep their shops running and growing.

Truck repair shop financing and automotive funding solutions may help qualified automotive businesses obtain capital for equipment, expansion, working capital, or other eligible business expenses. Automotive property financing, repair order software financing, and fleet vehicle repair financing can support facility purchases, technology improvements, and the equipment needed to maintain and repair commercial fleet vehicles.
Financing options designed around the needs of automotive repair and service businesses.
Get the funding you need to keep the parts, tires, and products your customers need in stock.
Upgrade the tools and equipment that help your technicians work efficiently and serve more customers.
Take your shop to the next level with financing options for improvements, expansion, and growth.
Whether you’re looking for equipment, inventory, construction, repairs, or expansion financing, start by telling us about your business and what you’re looking to accomplish.
Your shop is different from a typical business. Your financing needs can involve equipment, inventory, facilities, vehicles, tools, and expansion.
Whether you need inventory financing, construction financing, or funding for your next expansion, explore options for the needs that matter to your business.
When equipment needs replacing or inventory needs replenishing, access to the right financing can help you keep your business operating.
Opening another location? Expanding your garage? Adding services? Financing can help you turn your next business opportunity into a plan.
Whether you’re building a new garage, adding equipment, stocking up on inventory, or expanding your automotive business, Auto Shop Lend can help you explore financing options for your next move.
Affiliate Disclosure: We are an affiliate marketing website and may receive compensation from lending partners. We are not a lender, do not make credit decisions, and do not guarantee approval. Loan terms and rates are determined by individual lenders.
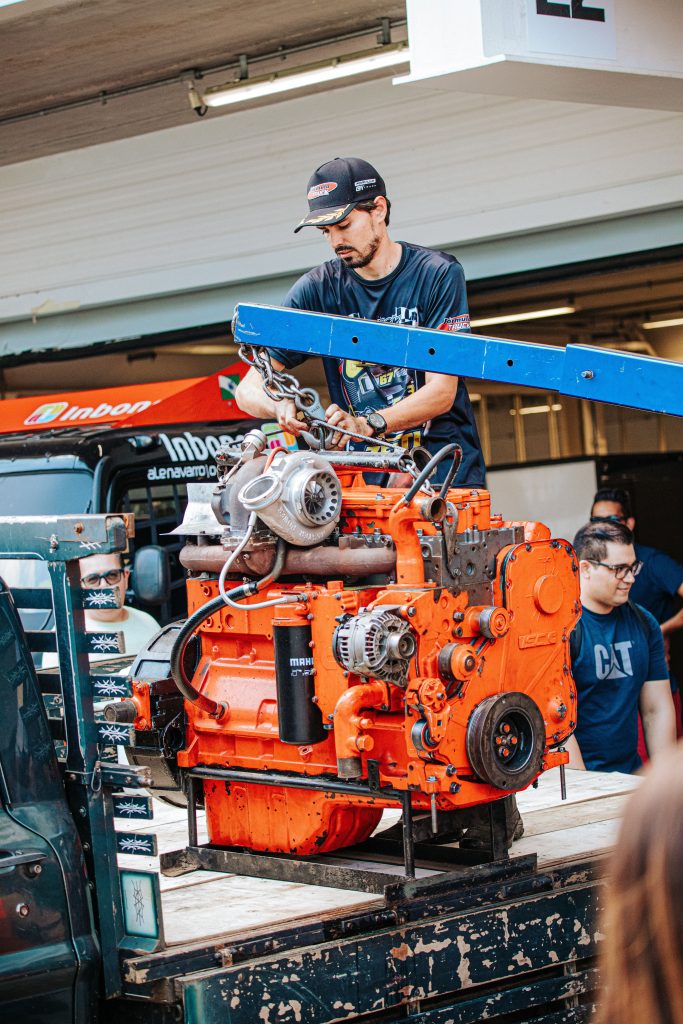
From everyday business needs to major expansion projects, explore financing options designed around automotive businesses and the work they do every day.
Auto Shop Lend focuses on financing for automotive businesses. The site helps shop owners explore financing options for business needs such as equipment, inventory, construction, expansion, and other shop-related expenses.
Depending on the financing option, funds may be used for business needs such as equipment, inventory, facility improvements, construction, expansion, and other qualified expenses.
Auto shops often need specialized equipment to operate and grow. Auto Shop Lend helps businesses explore financing options for equipment and other business needs.
Tire inventory can represent a significant expense for tire dealers and automotive service businesses. Inventory financing can help eligible businesses explore funding for stocking the products they need.
Garage construction financing can help eligible automotive businesses explore funding for building, expanding, or improving their facilities.
Yes. Auto repair shop expansion may require additional space, equipment, inventory, or facility improvements. Auto Shop Lend helps businesses explore financing options for these types of growth projects.
Transmission shops have specialized equipment, tools, inventory, and operating needs. Auto Shop Lend provides financing-focused resources for automotive businesses looking for funding options.
Automotive repair companies can face substantial capital requirements as they expand into commercial vehicle service, purchase property, modernize technology, and develop relationships with fleet customers. Heavy-duty equipment, larger facilities, diagnostic systems, software, inventory, and skilled employees can all require significant investment.
Financing can help qualified businesses spread these costs over time rather than funding every investment entirely from existing cash. The important issue is matching the type and term of financing to the investment being made. Long-lived assets such as real estate have different financing requirements than software, inventory, or short-term working capital.
The following nine areas can help automotive business owners develop a more disciplined approach to financing expansion.
Expanding into commercial vehicles can require different equipment and facilities from those needed for passenger cars. truck repair shop financing may help qualified businesses acquire eligible equipment, make facility improvements, or address other costs associated with establishing or expanding a heavy-duty repair operation.
Owners should also compare broader automotive funding solutions rather than assuming a single financing product is appropriate for every expense. Equipment, real estate, technology, acquisitions, and working capital can each have different financing structures.
Facility ownership can become particularly important as a company grows. automotive property financing may be considered when a qualified business wants to acquire, construct, refinance, or improve commercial real estate, depending on the financing program and eligibility requirements.
Technology deserves its own budget. repair order software financing may potentially help with eligible technology expenses associated with implementing systems that manage estimates, scheduling, work orders, technician workflow, parts, and customer communication.
Commercial customers can also create specialized capital requirements. fleet vehicle repair financing may help qualified businesses develop the equipment and operational capacity necessary to service larger numbers of commercial vehicles.
Before borrowing, management should prepare a detailed use-of-funds statement identifying exactly where every dollar will go.
Heavy-duty service can create opportunities for shops located near trucking companies, delivery businesses, contractors, municipalities, and other organizations operating commercial vehicles.
Businesses investigating truck repair shop financing should begin by identifying the vehicles they intend to service. Equipment requirements for light commercial vans can differ substantially from those associated with larger trucks.
Several automotive funding solutions can potentially be compared when planning an expansion. The appropriate structure depends on the business, lender, asset, borrower qualifications, and intended use of proceeds.
Physical space is another consideration. automotive property financing may become relevant when an existing building cannot accommodate larger vehicles, additional service bays, parking, parts storage, or new equipment.
Management technology should also scale with the operation. repair order software financing may be worth investigating when a company is implementing eligible systems designed to coordinate technicians, customers, parts, estimates, and work in progress.
Shops pursuing commercial accounts can evaluate fleet vehicle repair financing when capital is needed for eligible investments that increase their ability to maintain customer fleets.
Owners should avoid expanding solely because commercial repair tickets appear attractive. They should first evaluate local demand, competition, technician availability, expected equipment utilization, and the amount of working capital required during the expansion period.
Real estate can be one of the largest investments an automotive company makes. Purchasing a facility can provide greater control over the property, but ownership also introduces maintenance, taxes, insurance, and long-term financial obligations.
Qualified businesses researching automotive property financing should evaluate the complete cost of ownership rather than comparing a mortgage payment directly with monthly rent.
If the property will house commercial vehicle operations, truck repair shop financing might also be needed for equipment and improvements after the real estate transaction is completed.
Owners can compare multiple automotive funding solutions to determine whether property, machinery, renovations, and working capital should be financed separately or incorporated into a broader qualifying transaction.
Technology costs can easily be overlooked during a relocation. repair order software financing may potentially address eligible systems or implementation costs when a growing company needs improved operational technology.
A larger building can also make it possible to pursue commercial accounts. fleet vehicle repair financing could potentially support qualifying equipment or other investments associated with building that service capacity.
Location matters. Owners should evaluate accessibility, parking, vehicle storage, customer demographics, traffic patterns, competitors, building condition, permitted use, and the physical requirements of the intended operation before committing to a property.
Repair businesses increasingly depend on technology to manage daily operations. Digital estimates, vehicle histories, technician assignments, scheduling, parts ordering, customer approvals, invoices, and reporting can all be incorporated into modern management platforms.
repair order software financing may be considered when a qualified company wants to implement eligible technology without using a large portion of its available operating cash.
Technology can be especially useful when truck repair shop financing is supporting physical expansion. Adding service bays without improving scheduling and workflow systems could create administrative bottlenecks as repair volume increases.
Management should compare different automotive funding solutions based on the useful life and cost of the technology being acquired. A short-lived software investment generally should not automatically be treated the same way as long-lived real estate.
Businesses purchasing a new facility through automotive property financing can plan networking, computers, security, communications, and shop-management infrastructure as part of the broader relocation or expansion plan.
Companies pursuing recurring commercial accounts may also integrate technology with fleet vehicle repair financing because fleet customers can require accurate service histories, maintenance schedules, documentation, and reporting.
Before investing, owners should identify measurable objectives. Technology should solve an operational problem, improve visibility, reduce repetitive administrative work, or otherwise create practical value.
Consider a hypothetical automotive company preparing a $900,000 expansion. The figures below are purely illustrative. They are not industry averages, actual lender offers, recommended borrowing levels, or predictions of what a particular project will cost.
| Example Investment | Illustrative Amount |
|---|---|
| Property acquisition/improvements | $375,000 |
| Heavy-duty service equipment | $185,000 |
| Diagnostic equipment and tools | $105,000 |
| Technology and software | $70,000 |
| Parts and initial inventory | $90,000 |
| Working-capital reserve | $75,000 |
| Total | $900,000 |
Hypothetical allocation of capital across property, equipment, diagnostics, technology, inventory, and operating reserves.
$0$100K$200K$300K$400KProperty and impr…Heavy-duty equipmentDiagnostics and t…Parts and inventoryOperating reserveTechnology and so…
Illustrative example only. Actual costs and financing needs vary by business.
In this example, automotive property financing could potentially be researched for qualifying real estate expenditures, while truck repair shop financing might address eligible heavy-duty equipment.
Management could compare other automotive funding solutions for diagnostics, inventory, or working-capital requirements rather than automatically financing the entire project through one product.
The technology allocation might lead the company to investigate repair order software financing, while fleet vehicle repair financing could be evaluated for eligible investments associated with developing commercial service capabilities.
The important point is the budgeting process rather than the numbers themselves. Dividing an expansion into categories makes it easier to determine which investments are essential, which can wait, and which financing structure may be appropriate for each expense.
Automotive businesses may also investigate financing backed by the U.S. Small Business Administration. The SBA says its 7(a) program can be used for purposes including acquiring, refinancing, or improving real estate and buildings; short- and long-term working capital; refinancing certain business debt; purchasing and installing machinery and equipment; purchasing supplies; and ownership changes.
Those permitted uses can make the program worth investigating for businesses comparing automotive funding solutions, provided the company and intended transaction satisfy applicable requirements.
A company researching automotive property financing can discuss SBA-backed alternatives with participating lenders when acquiring or improving qualifying business property.
Similarly, truck repair shop financing may potentially involve SBA-backed financing when a qualifying project includes eligible machinery, equipment, real estate, or working-capital expenditures.
Businesses investigating repair order software financing should confirm with participating lenders whether their particular technology expenditures qualify rather than assuming every software expense is eligible.
The same caution applies to fleet vehicle repair financing. Eligibility depends on the specific transaction, use of proceeds, borrower, and program requirements.
The maximum individual 7(a) loan amount is currently $5 million, and SBA eligibility requirements include factors such as operating for profit, meeting applicable size standards, being creditworthy, and demonstrating a reasonable ability to repay.
Official SBA 7(a) Loan Program
SBA Lenders and Loan Program Information
Commercial fleet accounts can provide recurring repair opportunities, but they also require dependable service, sufficient capacity, accurate documentation, and strong operational management.
fleet vehicle repair financing may help qualified businesses invest in eligible equipment and capabilities needed to serve commercial customers.
A shop working on larger vehicles may combine this strategy with truck repair shop financing when specialized lifts, tools, diagnostic systems, or facility improvements are necessary.
Management should examine multiple automotive funding solutions instead of financing every expenditure identically. Long-lived machinery may justify a different repayment structure from short-term working capital or inventory.
If commercial growth requires additional space, automotive property financing could potentially support an eligible facility acquisition or improvement project.
Technology also becomes more important as account volume increases. repair order software financing may help a qualified business implement eligible systems for maintenance records, scheduling, estimates, invoices, technician assignments, and customer communication.
Commercial customer concentration deserves careful attention. A shop that invests heavily to serve one fleet could become vulnerable if that customer changes vendors. Building relationships with several commercial accounts can reduce dependence on a single source of revenue.
Service agreements should also clearly establish billing procedures, payment expectations, authorization requirements, and responsibility for additional repairs discovered during service.
One of the most important financing principles is matching repayment obligations with the expected useful life and economic value of the investment.
automotive property financing typically involves an asset with fundamentally different characteristics from technology or inventory. Owners should therefore avoid choosing financing solely on the basis of the smallest advertised payment.
The same analysis applies to truck repair shop financing. Heavy-duty equipment expected to remain productive for many years should be evaluated according to purchase price, installation, maintenance, utilization, and expected useful life.
Businesses comparing automotive funding solutions should review total borrowing cost, repayment frequency, fees, collateral requirements, guarantees, prepayment terms, and other contractual provisions.
Technology financed through repair order software financing may have a shorter useful life than a building or major piece of machinery, making the financing term especially important.
Companies considering fleet vehicle repair financing should likewise estimate whether additional commercial revenue can reasonably support the resulting payments.
Federal tax treatment is another consideration. IRS Publication 946 explains depreciation and the rules governing qualifying business or income-producing property. The IRS notes that depreciable tangible property can include machinery, vehicles, furniture, equipment, and buildings when applicable requirements are satisfied.
IRS Publication 946 — How to Depreciate Property
Tax outcomes vary by taxpayer and asset, so businesses should consult a qualified tax professional before relying on a particular depreciation treatment.
Borrowing should support a business plan rather than become the business plan.
Before obtaining truck repair shop financing, management should estimate commercial service demand, technician availability, equipment utilization, margins, and working-capital requirements.
When comparing automotive funding solutions, owners should determine which costs genuinely need financing and which can reasonably be funded through existing cash flow.
Businesses investigating automotive property financing should evaluate the property as both a physical facility and a long-term financial commitment. A larger building provides little benefit if customer demand cannot support its operating and financing costs.
Companies researching repair order software financing should establish measurable goals for their technology investment. These might include improving scheduling, reducing administrative work, providing better reporting, or making repair information easier for technicians and customers to access.
Finally, fleet vehicle repair financing should support realistic commercial demand. Owners should avoid purchasing expensive specialized equipment based entirely on projected work that has not materialized.
Additional information about automotive business capital is available on the AutoShopLend homepage.
AutoShopLend should be used as a financing-resource and lender-matching starting point rather than as a guarantee of financing. Approval, amounts, rates, fees, and repayment terms depend on the financing provider and applicant qualifications.
Commercial vehicle repair can create meaningful growth opportunities for automotive businesses, but expansion requires careful financial planning. Property, heavy-duty machinery, diagnostics, technology, inventory, technicians, and operating reserves all have different economic characteristics.
A detailed project budget allows management to identify exactly where capital is required. It also makes it easier to compare financing products based on the asset being purchased rather than simply accepting whichever source offers the largest amount.
Owners should create conservative cash-flow projections and consider what happens if a new location, fleet contract, or service department grows more slowly than anticipated. Preserving adequate working capital can be just as important as acquiring equipment.
Government resources from the SBA and IRS can provide useful information when evaluating financing and tax considerations, but eligibility and tax treatment depend on the individual circumstances involved.